
Weekly Wisdom: Financials Remain Attractive Among Interest Cap Volatility
Interest Rate Cap Rhetoric is Creating Headlines, Not Lasting Risk
Over the weekend, President Trump called for a one-year cap of 10% on credit card interest rates, generating volatility across consumer lending stocks, particularly among card-focused issuers. While in theory, a hard cap could pressure card yields, reduce credit availability for higher-risk borrowers, and alter consumer behavior. However, we believe the real impact will be limited compared to current market sentiment. Given the difficulty of implementation, combined with the competitive nature of the market, the overwhelmingly prime credit mix at most large banks, and multiple levers issuers can deploy, such as higher fees, lower rewards costs, and tightening underwriting, we expect any effect on earnings to be modest.
Legislative and Practical Barriers Remain High
In practice, legal and practical hurdles make implementation uncertain. Legal authority for such a move is unclear, and any attempt to impose a hard cap via executive order would almost certainly face immediate court challenges and delays. Formal rulemaking through regulatory agencies would take months to complete, far too long to deliver relief before the midterms. In addition, previous efforts to legislate similar proposed interest caps in 2025 and again in 2019 failed amid strong industry and political opposition, illustrating how difficult it is to enforce even with bipartisan support. Analysts have highlighted hesitance in implementation with a Bloomberg report stating a mere 30% probability of success by 2026.1 Taken together, these factors make it highly unlikely that the current proposal, as framed by President Trump, will translate into meaningful policy in the near term.
A Competitive Market Limits the Case for Intervention
The credit card industry remains highly competitive, with consumers able to choose among cards, installment loans, unsecured and secured credit lines, and mortgages. There is little evidence of market failure. A May 2025 New York Fed study showed that only 46% of cardholders carried a balance at least once during the past year, while less than 20% of available credit card lines are utilized.2 A broad rate cap could therefore eliminate interest-free grace periods, raise minimum payments, and restrict access to credit for lower-FICO borrowers, outcomes that previously fueled opposition to the five-year proposal.
Credit Quality and Diversification Limit Downside Risk
From a credit standpoint, large banks remain overwhelmingly positioned toward prime borrowers. Bank of America reports an average FICO score of 777, with only 12% of borrowers below 660.3 JPMorgan disclosed a weighted-average FICO score of 7744, while Wells Fargo’s largest segment of credit card balances is held by borrowers with FICO scores above 740.5 Capital One remains the exception, with 27% of its domestic card portfolio carrying FICO scores of 660 or below, though that exposure has declined following the Discover acquisition.6 At the same time, credit card income represents a modest share of earnings for diversified banks, accounting for 6.2% of net interest income at JPMorgan, 10.5% at Bank of America, and 12.4% at Wells Fargo.7 These factors leave banks well-positioned to absorb any potential impact from a rate cap, making meaningful earnings disruption unlikely.
Financials Have Multiple Offsets to Protect Earnings
Even in a hypothetical scenario where pricing pressure were introduced, large financial institutions have numerous levers to protect profitability. These include higher annual and ancillary fees, reduced rewards and loyalty costs, tighter underwriting standards, and lower operating expenses tied to marketing and customer acquisition. Improving credit trends provide an additional offset, as delinquencies, down -13 bps year-over-year, and net charge-offs, down -43 bps year-over-year, have continued to track favorably relative to historical norms, supporting expectations for lower credit costs into 2026.8
Taken together, we believe concerns around a credit card interest rate cap are overstated. Past efforts to impose a multi-year cap have failed, and the current proposal faces similar structural, legal, and political hurdles. With strong credit quality, improving loss trends, diversified earnings streams, and multiple operational offsets, financial institutions are well-positioned to manage through the current policy noise. We remain constructive and bullish on the financial sector and view recent volatility as an opportunity rather than a change in underlying fundamentals.
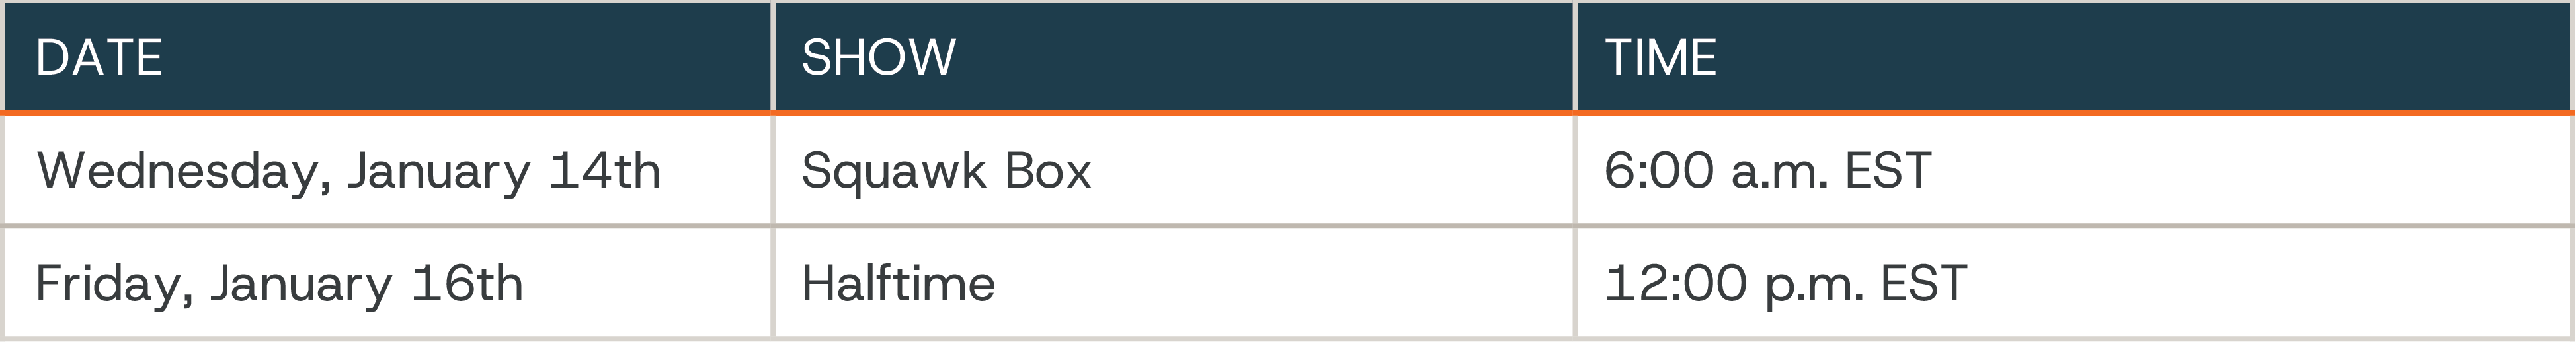
Stephanie Link’s TV Schedule
1 BI Policy Watch: Credit-Care Rate Cap’s Long Odds, as of December 2025
2 Federal Reserve Bank of NY, as of May 2025
3 Bank of America, as of November 2025
4 JP Morgan, as of May 2025
5 Wells Fargo, as of October 2025
6 Capital One, as of October 2025
7 Bloomberg, as of December 2025
8 Barclays, as of October 2025
This material is for general information and educational purposes only. Information is based on data gathered from what we believe are reliable sources. It is not guaranteed as to accuracy, does not purport to be complete and is not intended to be used as a primary basis for investment decisions.
Find answers to your questions about Hightower Signature Wealth
Hightower Signature Wealth is a fiduciary wealth management practice that provides investment management, financial planning, estate strategies, insurance, and banking solutions. We work with families, business owners, professionals, women, and retirees across more than 40 offices nationwide. Our advisors take the time to understand your financial priorities, develop a plan around your goals, and adjust that plan as your life and circumstances evolve.
Hightower Signature Wealth provides a broad range of wealth management services designed to address different aspects of your financial life. Our capabilities include investment management, financial planning, retirement planning, estate strategies, insurance and risk management, banking solutions, and charitable giving strategies. By considering these areas together, our advisors can develop a coordinated approach based on your goals, priorities, financial circumstances, and plans for the future.
Hightower Signature Wealth advisors work with a broad range of clients, including women, families, business owners, professionals, retirees, and high-net-worth individuals navigating major life or financial transitions. Rather than applying a generic playbook, each advisor tailors the plan to a client’s specific goals and current stage of life – from early-career decisions to multigenerational wealth transfer.
Yes. Hightower Signature Wealth advisors serve as fiduciaries, which means they are committed to acting in their clients’ interests when providing investment advice. We offer fee-based advisory services, with fees depending on the services provided and the specifics of your relationship. Your advisor will discuss the applicable fee structure with you so you can understand how you are charged and what services are included.
Hightower Signature Wealth has more than 40 offices nationwide, allowing our advisors to serve individuals, families, and organizations across the country. Depending on your location and preferences, you may be able to work with an advisor locally or connect with a team in another market. Visit our Locations page to explore our office locations, learn more about the teams in each market, and find an office near you.
Getting started with Hightower Signature Wealth is simple. Complete our online contact form with some basic information about yourself and what you are looking for, and we’ll connect you with an advisor who can discuss your needs and financial priorities. That initial conversation is an opportunity to learn more about our approach, ask questions, and determine whether working with a Hightower Signature Wealth advisor may be a good fit.
Your first conversation is an opportunity for us to learn more about you, your financial circumstances, and what you hope to accomplish. An advisor may ask about your goals, current investments, family considerations, business interests, and other priorities that could influence your financial plan. You’ll also have an opportunity to ask questions, learn about our approach, and discuss what working together could look like.
