
Weekly Wisdom: Powering AI Amid a Tightening Energy Market
Iran Conflict Further Constrains Global Energy Supply
Tensions between the U.S. and Iran escalated again this week, increasing concerns about the availability of global oil and natural gas supplies. The U.S. military destroyed five Iranian tankers after Iran’s Islamic Revolutionary Guard Corps attempted to strike a U.S. Navy warship with ballistic missiles. Tehran responded by promising decisive action and warned that ships entering a restricted area near the Strait of Hormuz would face sanctions.1 The Strait remains one of the most important energy chokepoints in the world as approximately one-fifth of global oil and liquefied natural gas passed through Hormuz before the conflict. Current crude flows have fallen to 10 million barrels per day, half their prewar level, as tankers continue to face the risk of attack.2 While some vessels are still moving through the Strait with their tracking systems turned off, these shipments remain inconsistent and difficult to quantify. The escalation has additionally expanded beyond Hormuz as Iran-backed Houthi militants have attacked energy infrastructure in Saudi Arabia, including facilities near the 400,000-barrel-per-day Jazan refinery. Several Saudi energy sites were temporarily halted, adding to concerns that the conflict could further disrupt production, refining, and transportation throughout the region.3
Not surprisingly, energy prices have responded. Brent crude moved above $100 per barrel for the first time since July, while West Texas Intermediate reached approximately $95.4 Global oil inventories held aboard ships have declined by more than 150 million barrels since the middle of July. Refined products such as diesel have tightened even more sharply as the Middle East conflict combines with the Russia-Ukraine war to constrain supplies.5 Natural gas markets are experiencing similar pressure. European benchmark gas prices have risen almost 10% since the prior Friday and reached their highest level since January 2023. European storage facilities are only 67% full compared with a five-year average of 84%, while Germany’s storage is approximately 55% full. Pipeline deliveries to Europe also declined 9% in September, increasing the region’s reliance on LNG ahead of the winter heating season.6 While the market is not yet facing a physical shortage, but the combination of low inventories, disrupted shipments, and competition between European and Asian buyers should continue to support natural gas prices.
AI Driving Further Energy Demand
The tightening supply picture comes as U.S. electricity demand is entering its strongest period of growth in years. Electricity consumption is projected to increase approximately 5.7% annually from 2025 through 2030, driven by artificial intelligence, digital infrastructure, and broader electrification. AI-related power-demand estimates have already increased to 90 gigawatts from 75 gigawatts. Over the next decade, data centers are projected to account for 75% of total U.S. electricity-demand growth, requiring 30 gigawatts of new power capacity each year.7 While interconnection queues have reached 726 gigawatts, nine times projected 2030 IT demand, high-voltage transmission upgrades routinely require more than a decade to complete. The U.S. could therefore face a net capacity deficit of 30 to 55 gigawatts by 2030, with the most significant bottlenecks concentrated in major data-center markets such as Virginia, Texas, and Ohio.8 This dynamic helps oppose concerns about overbuilding as unlike the single-purpose fiber-optic networks developed during the early 2000s, power-generation and transmission assets can serve the broader economy even if AI demand falls short of expectations. The system will also need to replace 50 to 75 gigawatts of retiring coal and thermal generation while supporting broader industrial electrification showing how there is a greater risk in not building enough rather than overbuilding.9
Natural Gas Will Power the AI Buildout
Natural gas is rapidly becoming the most practical near-term solution to the power shortage. Approximately 80% of expected AI data-center demand is estimated to be powered directly or indirectly by natural gas.10 Gas generation offers the reliability, scalability, and speed of deployment needed as utilities struggle to meet rapidly tightening power timelines. Data-center operators are increasingly moving behind the meter to avoid lengthy grid-interconnection delays. More than 50% of power-sector leaders expect to maintain permanent on-site generation by 2030, while 64% favor natural gas because it can provide dependable around-the-clock power.11 Some companies are also considering locating data centers near major gas basins to avoid pipeline-permitting constraints.
Increased renewable adoption also strengthens the case for natural gas. Renewables are expected to account for approximately 30% of the power needed to support AI computing growth.12 A significant portion of that renewable energy is likely to come from solar-plus-battery energy storage solutions as hyperscalers sign virtual solar power-purchase agreements to offset emissions associated with natural gas generation. However, due to the nature of solar and wind generation, which added capacity is intermittent. While renewables can help during peak demand, the grid requires flexible power sources that can quickly balance changes in production. We believe natural gas should therefore benefit both directly from rising AI power consumption and indirectly from the continued expansion of renewable generation serving as the backbone of power capacity.
U.S. LNG and Midstream Infrastructure Benefit
Domestic power demand is rising while international buyers are becoming more reliant on U.S. natural gas. U.S. LNG exports will grow approximately 13% annually from 2024 through 2032, reaching 35 billion cubic feet per day compared with approximately 16 billion cubic feet per day this year. The U.S. Energy Information Administration also expects North American LNG export capacity to double by 2030.13 International demand is also being supported by natural gas as a feedstock for plastics, petrochemicals, ammonia, methanol, and steelmaking. Recent agreements reinforce the appeal of secure U.S. supply. Cheniere signed a 25-year agreement to supply CPC Corporation with 1.2 million metric tons of LNG annually, while Venture Global signed an agreement to supply TotalEnergies with approximately 0.85 million metric tons annually for five years beginning in 2026.14
The growth in AI power demand and LNG exports creates an attractive opportunity for midstream infrastructure. Approximately 4.57 billion cubic feet per day of additional Permian pipeline capacity is expected to enter service by the end of 2026, followed by another 3.7 billion cubic feet per day from the Eiger pipeline by mid-2028.15 Because these pipelines are highly contracted, they should generate visible earnings growth for the participating companies. Importantly, U.S. midstream operators have limited direct exposure to lost Persian Gulf volumes but remain as economic beneficiaries to the disruption. As international supplies tighten, the U.S. becomes an increasingly important provider of crude oil, LNG, liquefied petroleum gas, and refined products. This should support higher utilization across pipelines, processing facilities, and export terminals. Higher prices are also improving the outlook for U.S. oil producers and oilfield-services companies. U.S. rig counts have increased 8% in 2026 following a 32% decline between 2022 and 2025, and the year-end forecast of 650 rigs implies further gains from recent levels.16 Overall, AI, electrification, LNG expansion, power-plant retirements, and constrained global supplies are converging to create a multiyear investment opportunity across natural gas, oil, midstream infrastructure, and energy services.
Stephanie Link’s TV Schedule
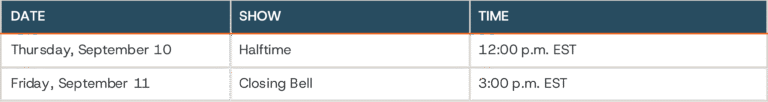
[1] Bloomberg Intelligence, As of September 9, 2026
[2] UBS Analyst Note, As of July 28, 2026
[3] Bloomberg Intelligence, As of September 7, 2026
[4] Bloomberg, As of September 9, 2026
[5] Bloomberg Intelligence, As of August 26, 2026
[6] Bloomberg Intelligence, As of September 9, 2026
[7] UBS Analyst Note, As of July 25, 2026
[8] UBS Analyst Note, As of September 6, 2026
[9] UBS Analyst Note, As of September 6, 2026
[10] UBS Analyst Note, As of September 6, 2026
[11] UBS Analyst Note, As of September 6, 2026
[12] Bloomberg Intelligence, As of June 3, 2026
[13] U.S. Energy Information Administration, As of October 16, 2025
[14] UBS Analyst Note, As of March 8, 2026
[15] UBS Analyst Note, As of March 24, 2026
[16] Bloomberg Intelligence, As of September 3, 2026
This material is for general information and educational purposes only. Information is based on data gathered from what we believe are reliable sources. It is not guaranteed as to accuracy, does not purport to be complete and is not intended to be used as a primary basis for investment decisions.
Find answers to your questions about Hightower Signature Wealth
Hightower Signature Wealth is a fiduciary wealth management practice that provides investment management, financial planning, estate strategies, insurance, and banking solutions. We work with families, business owners, professionals, women, and retirees across more than 40 offices nationwide. Our advisors take the time to understand your financial priorities, develop a plan around your goals, and adjust that plan as your life and circumstances evolve.
Hightower Signature Wealth provides a broad range of wealth management services designed to address different aspects of your financial life. Our capabilities include investment management, financial planning, retirement planning, estate strategies, insurance and risk management, banking solutions, and charitable giving strategies. By considering these areas together, our advisors can develop a coordinated approach based on your goals, priorities, financial circumstances, and plans for the future.
Hightower Signature Wealth advisors work with a broad range of clients, including women, families, business owners, professionals, retirees, and high-net-worth individuals navigating major life or financial transitions. Rather than applying a generic playbook, each advisor tailors the plan to a client’s specific goals and current stage of life – from early-career decisions to multigenerational wealth transfer.
Yes. Hightower Signature Wealth advisors serve as fiduciaries, which means they are committed to acting in their clients’ interests when providing investment advice. We offer fee-based advisory services, with fees depending on the services provided and the specifics of your relationship. Your advisor will discuss the applicable fee structure with you so you can understand how you are charged and what services are included.
Hightower Signature Wealth has more than 40 offices nationwide, allowing our advisors to serve individuals, families, and organizations across the country. Depending on your location and preferences, you may be able to work with an advisor locally or connect with a team in another market. Visit our Locations page to explore our office locations, learn more about the teams in each market, and find an office near you.
Getting started with Hightower Signature Wealth is simple. Complete our online contact form with some basic information about yourself and what you are looking for, and we’ll connect you with an advisor who can discuss your needs and financial priorities. That initial conversation is an opportunity to learn more about our approach, ask questions, and determine whether working with a Hightower Signature Wealth advisor may be a good fit.
Your first conversation is an opportunity for us to learn more about you, your financial circumstances, and what you hope to accomplish. An advisor may ask about your goals, current investments, family considerations, business interests, and other priorities that could influence your financial plan. You’ll also have an opportunity to ask questions, learn about our approach, and discuss what working together could look like.
