AI Concerns Rise, but Growth Continues to Accelerate
AI Concerns Return
Concerns around the AI trade increased following weakness among “neocloud” companies, which build data centers and rent access to AI chips and computing capacity. Elice, a South Korean AI computing provider, fell 32% in its public-market debut despite already operating data centers, holding government contracts, and generating profits. The disappointing debut suggested that investors are becoming more cautious toward capital-intensive AI.1 Additionally, CoreWeave led a recent decline in AI names after its bonds fell to levels typically associated with financial distress. This headline raised concerns about whether its highly leveraged business model can continue funding its rapid infrastructure expansion. Its shares fell approximately 20% over the past week and are now more than 60% below their peak.2
However, we believe the market is drawing too broad a conclusion from these headlines resulting in an overstated impact. The issues discussed in these headlines primarily highlight company-specific financing and execution risks rather than a slowdown in the AI Cycle. Demand for computing power remains strong, AI adoption continues to expand, and the largest platforms are beginning to demonstrate tangible revenue and earnings contributions from their investments. This momentum continues even as investors become more selective about which companies are best positioned to finance and monetize that growth.
SpaceX Delivers Another Massive Quarter
SpaceX demonstrated strong growth as it beat expectations across earnings, revenue, and nearly every major business segment. Revenue reached $14.58 billion, approximately 13% above expectations, while earnings per share came in at $0.35 compared with the $0.15 estimate. Operating income surged to $2.79 billion from a loss of $143 million in the prior quarter, while adjusted EBITDA exceeded $8 billion.3 The strong results pushed shares sharply higher following the report and helped lift sentiment across the broader AI trade. The biggest surprise was the AI segment, also known as Super Intelligence (SI), which overtook Connectivity as SpaceX’s largest source of revenue. SI revenue reached $7.56 billion, up from $2.56 billion in the prior quarter, and operating income improved to $431 million from a loss of $1.26 billion. SpaceX also added $6.7 billion of incremental SI solutions and infrastructure revenue from the prior year, supported by cloud-service agreements, the acquisition of Cursor and growing adoption of its AI models and software applications.4
Importantly, this is beginning to show that AI investment can translate into real revenue and operating leverage. SpaceX’s nameplate computing capacity reached 1.7 gigawatts at the end of September, while Grokbot reached 800,000 paid users in early October, double its September user base. Management expects Grokbot to consume most of the company’s SI computing capacity for the foreseeable future, suggesting that demand is already absorbing much of the infrastructure being built. SpaceX spent approximately $19.6 billion during the quarter, including $16.44 billion within SI. However, both total and SI capital expenditures were approximately in line with or below expectations. More importantly, the rapid improvement in SI revenue and profitability provides evidence that this spending is supporting a growing business rather than simply accumulating without a clear path to monetization.5
Starlink and Space Operations Add More Growth Channels
Along with the SI segment, Connectivity revenue increased 22% sequentially and 69% from the prior year. Consumer revenue grew 57% year-over-year, while enterprise and government revenue increased 91%. Starlink finished the quarter with 13.6 million subscribers, up from 12 million in the previous quarter. The announcement that Starlink plans to become a major U.S. mobile carrier adds another catalyst for growth in its subscriber count for the future. SpaceX intends to begin launching Starlink Mobile V2 satellites aboard Starship in 2027 and will use its expanded wireless-spectrum portfolio to grow its direct-to-cell service. The company also agreed to acquire additional 800 MHz spectrum licenses, with the transaction expected to close during the first half of 2027. This could materially expand Starlink’s addressable market beyond traditional satellite internet. Management was also highly encouraged by Starship Flight 14, which deployed 26 Starlink V3 satellites. A single Starship launch can add roughly ten times the downlink capacity of a Falcon 9 Starlink launch, potentially improving the economics and speed of expanding the constellation. SpaceX now has Starlink installed on more than 3,800 aircraft and continues to see strong enterprise and government adoption.6
The traditional Space segment also performed well. Revenue reached $1.77 billion, increasing 84% sequentially, while adjusted EBITDA returned to positive territory. SpaceX expanded its pipeline by signing three additional NASA crew missions, 18 National Security Space Launch missions, three commercial Starfall missions and a contract to deliver a payload to the lunar surface using Starship. The company also announced plans for Starbase, Louisiana, a next-generation spaceport designed to eventually support thousands of Starship flights annually. Taken together, SpaceX is developing several complementary growth engines across AI computing, software, satellite connectivity, mobile communications, and launch services. That diversification is particularly important because it gives the company multiple ways to monetize its infrastructure investments.7
Meta’s Muse Shows Early Adoption and Monetization
Meta is providing another encouraging AI data point through the early adoption of its Muse personal assistant. Muse has generated more than 10.4 million downloads and briefly overtook ChatGPT at the top of the App Store. Early U.S. downloads also exceeded those of both ChatGPT and Sora, benefiting from Meta’s enormous installed base across Instagram, WhatsApp, and Facebook.8 Muse remains early in its development, and overall adoption is still relatively low compared with Meta’s broader user base. Meta is currently offering a free basic tier, subscriptions for higher usage, and small transaction fees from partners. Advertising could eventually become another meaningful revenue stream as engagement expands. That combination is important as Meta can use its existing platforms to distribute Muse at a scale that few competitors can match, while monetizing adoption through subscriptions, transaction fees and eventually advertising. Muse Wonder, which targets enterprises and developers, can also support the consumer product and broaden Meta’s opportunity beyond its traditional advertising business. Meta’s quarterly capital expenditures are expected to more than double as the company expands its AI infrastructure, placing near-term pressure on free cash flow. However, analysts have raised longer-term earnings expectations despite the higher spending, citing stronger advertising growth and the potential for new AI products to create additional revenue.9
We continue to view the recent anxiety around AI as a normal shift from indiscriminate enthusiasm toward greater selectivity. Capital intensity, financing structures, and execution will matter, and weaker companies may struggle. But the latest developments do not indicate that AI demand is slowing. SpaceX is producing rapid revenue growth and positive operating leverage from its SI investments, while Meta is demonstrating that new AI products can achieve significant adoption and establish several potential monetization channels. While volatility will likely remain elevated, we believe concerns about a broad slowdown are overstated and remain bullish on the long-term opportunity across AI, data centers, connectivity, and the supporting infrastructure required to power that growth.
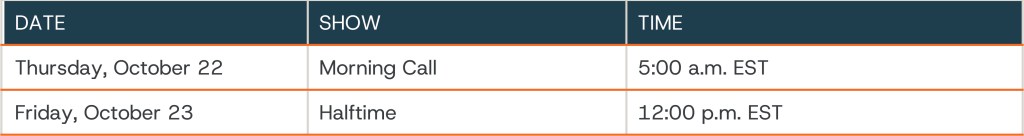
Stephanie Link’s TV Schedule
[1] Bloomberg, as of October 21, 2026
[2] Bloomberg, as of October 21, 2026
[3] SPCX 3Q26 Earnings Call, as of October 20, 2026
[4] SPCX 3Q26 Earnings Call, as of October 20, 2026
[5] SPCX 3Q26 Earnings Call, as of October 20, 2026
[6] SPCX 3Q26 Earnings Call, as of October 20, 2026
[7] SPCX 3Q26 Earnings Call, as of October 20, 2026
[8] Bloomberg Intelligence, as of October 21, 2026
[9] Wells Fargo Analyst Note, as of September 20, 2026
This material is for general information and educational purposes only. Information is based on data gathered from what we believe are reliable sources. It is not guaranteed as to accuracy, does not purport to be complete and is not intended to be used as a primary basis for investment decisions.
Find answers to your questions about Hightower Signature Wealth
Hightower Signature Wealth is a fiduciary wealth management practice that provides investment management, financial planning, estate strategies, insurance, and banking solutions. We work with families, business owners, professionals, women, and retirees across more than 40 offices nationwide. Our advisors take the time to understand your financial priorities, develop a plan around your goals, and adjust that plan as your life and circumstances evolve.
Hightower Signature Wealth provides a broad range of wealth management services designed to address different aspects of your financial life. Our capabilities include investment management, financial planning, retirement planning, estate strategies, insurance and risk management, banking solutions, and charitable giving strategies. By considering these areas together, our advisors can develop a coordinated approach based on your goals, priorities, financial circumstances, and plans for the future.
Hightower Signature Wealth advisors work with a broad range of clients, including women, families, business owners, professionals, retirees, and high-net-worth individuals navigating major life or financial transitions. Rather than applying a generic playbook, each advisor tailors the plan to a client’s specific goals and current stage of life – from early-career decisions to multigenerational wealth transfer.
Yes. Hightower Signature Wealth advisors serve as fiduciaries, which means they are committed to acting in their clients’ interests when providing investment advice. We offer fee-based advisory services, with fees depending on the services provided and the specifics of your relationship. Your advisor will discuss the applicable fee structure with you so you can understand how you are charged and what services are included.
Hightower Signature Wealth has more than 40 offices nationwide, allowing our advisors to serve individuals, families, and organizations across the country. Depending on your location and preferences, you may be able to work with an advisor locally or connect with a team in another market. Visit our Locations page to explore our office locations, learn more about the teams in each market, and find an office near you.
Getting started with Hightower Signature Wealth is simple. Complete our online contact form with some basic information about yourself and what you are looking for, and we’ll connect you with an advisor who can discuss your needs and financial priorities. That initial conversation is an opportunity to learn more about our approach, ask questions, and determine whether working with a Hightower Signature Wealth advisor may be a good fit.
Your first conversation is an opportunity for us to learn more about you, your financial circumstances, and what you hope to accomplish. An advisor may ask about your goals, current investments, family considerations, business interests, and other priorities that could influence your financial plan. You’ll also have an opportunity to ask questions, learn about our approach, and discuss what working together could look like.