2026 Investment Forum Recap
2026 Hightower Investment Forum
The Hightower Investment Solutions team wants to give a big thank-you to the Hightower community, advisors, speakers, and sponsors for joining us at the Conrad in New York City for the 2026 Hightower Investment Forum! We had two action-packed days full of insightful conversations on the economy, public markets, politics, artificial intelligence, and emerging investment opportunities, helping connect each speaker’s views to the opportunities and risks facing investors today.
Our Investment Themes
We kicked off Investment Forum highlighting the current constructive outlook on the economy, as the Atlanta Fed’s GDP tracker stood at 3.5%, supported by resilient consumers, business investment, and AI-related spending.1 The labor market continues to be strong as job openings increased 5% year over year, private payrolls have grown for 16 consecutive months, announced layoffs are down 71%, and retail sales have grown more than 4% during the past six months.2 Corporate fundamentals also remain strong, with earnings growing roughly 25%–30%, double-digit revenue growth, and expanding margins across more than just technology. At the same time, the S&P 500’s valuation has fallen from 22 times earnings in January to 17.7 times, while the equal-weighted index has outperformed the market-cap-weighted index, signaling healthier market breadth.3 We do not believe political uncertainty will end the AI cycle, as even a pessimistic forecast of a 25%–30% slowdown in data-center construction would still leave trillions of dollars of long-term investment and significant demand for power and grid infrastructure.4 We are also focused on cybersecurity, robotics, women’s health, GLP-1 medications, the creator economy, cryptocurrency, space, quantum computing, and Brazil as important long-term investment themes. Overall, during periods of volatility backed by constructive market fundamentals, investors benefit the most by find opportunities in durable themes and continuing to hold strong.
Consumer and Labor Market Insights
Don Rissmiller of Strategas joined us discussing the economic cycle, inflation, and the consumer. Don’s base case is a midcycle slowdown rather than a recession, pointing to approximately 3.5% real GDP growth, a 21% increase in corporate profits, and a 90% increase in data-center construction through September.5 He described the consumer as “E-shaped” rather than “K-shaped,” with upper-income households supported by wealth, middle-income households benefiting from a stable labor market, and lower-income households supplementing wages through gig work and small-business formation. With labor-force growth slowing, Don estimates that the number of monthly jobs needed to keep unemployment stable may have fallen from approximately 150,000 several years ago to only 25,000–30,000 today.6 Don also sees significant room for AI-related productivity gains, as measurable efficiencies have so far appeared primarily in technology, finance, and business services, which represent only about 20% of the labor force.
Technical View of Market Volatility
Bob Lang provided helpful insight into market volatility, technical indicators, and the role of options in portfolios. VIX recently increased approximately 70% in one session, rising from roughly 16–17 to nearly 27 in one of its largest percentage moves since the index was introduced.7 Although the charts looked weak following the selloff, he viewed the volatility as a potential buying opportunity because sharp spikes in investor fear have historically created attractive entry points. Bob was encouraged by improving market breadth, particularly the recent outperformance of the equal-weighted S&P 500, as money has begun moving beyond a small group of large technology companies.8 From a sector perspective, he highlighted strength in defense and retail, while tight high-yield credit spreads continue to signal that markets are not pricing in an imminent recession. Bob also discussed covered calls as a way to generate income and put options as a form of portfolio protection that can help investors remain disciplined rather than selling during periods of extreme volatility.
The Economic Cycle and Productivity Gains
Dennis DeBusschere and Jordi Visser of 22V joined Stephanie Link to discuss financial conditions, inflation, market positioning, and the next phase of artificial intelligence. Dennis’s quantitative work indicates a roughly 99% probability that the economy remains in a normal expansion, with strong household balance sheets lowering the risk of a major downturn. He believes tighter financial conditions should slow inflation over the next six to 12 months, helping extend the cycle and creating opportunities to buy market pullbacks. Jordi estimated that approximately $1.5 trillion has been raised this year to support AI investment and viewed the recent correction as a healthy development that could introduce greater capital discipline without stopping the buildout.9 Dennis noted that raising annual productivity growth from 2% to 2.5% could add approximately $10 trillion of U.S. economic output over a decade.10 Despite potential permitting and policy delays, they believe hyperscalers have sufficient capital to meet their 2027 commitments and that the broader AI transformation could require approximately $90 trillion of investment over the next 10–15 years.11
The Continuation of the AI Trade
Josh Brown and Bryn Talkington joined the stage discussing the election-driven selloff, market concentration, and the next stage of the AI investment cycle. Both viewed the market’s initial reaction as an overreaction, with Bryn arguing that new data-center requirements could slow development but would not stop projects in business-friendly states such as Texas. She believes a more measured pace could benefit companies with existing capacity, make early data-center investments more valuable, and ultimately extend the cycle. Josh explained that algorithmic trading, leveraged products, and newer retail accounts can turn a normal 2%–3% reaction into a much larger selloff, but noted that the VIX quickly fell from 28 to 20 as the pressure faded.12 Neither believes market concentration is a reason to avoid U.S. equities, as every bull market has been led by its most important companies and index leadership changes as businesses strengthen or weaken. They also highlighted improving breadth, with 69% of S&P 500 companies trading above their 50-day moving averages and energy leading the market despite representing only a small share of the index.13 Their larger takeaway was that the next phase of the AI story will depend on companies demonstrating that their investments are improving efficiency, earnings, and business operations, which could support broader participation and multiple expansion.
Disinflation, Market Breadth, and Semiconductors
Victoria Greene, Adam Parker, and Chris Verrone joined Stephanie Link to discuss whether 2027 could mark a shift toward disinflation, broader market leadership, and renewed strength in semiconductors. Chris highlighted oil declining approximately 20% from its highs, falling crack spreads and grains, lower inflation breakevens, and improving consumer sectors as signs that the macro environment could become more supportive.14 Victoria viewed the slower pace of data-center development as a rational adjustment that could encourage more responsible construction without stopping the long-term buildout. She remains a “reluctant bull,” favoring a balanced portfolio with quality companies, strong free cash flow, healthcare exposure, and investments that are less closely tied to AI. Adam agreed that the U.S. economy has been stronger than widely perceived and believes the semiconductor industry remains in an eight- to 10-year investment cycle. Chris similarly believes the recent indiscriminate selling could indicate that semiconductors are forming a tradable bottom, although the sector may require time to repair the technical damage. Together, the panel remained constructive on the long-term opportunity while emphasizing diversification, discipline, and the importance of looking beyond short-term headlines.
Technology, AI Financing, and Sector Opportunities
Dan Ives, Richard Farr, and Bill Baruch joined Stephanie Link to discuss the data-center buildout, AI financing, software, cybersecurity, and opportunities beyond technology. Dan estimated that only 10%–20% of planned data centers may not be completed, noting that approximately 75% of projects scheduled for the next several years have already received permits and that demand continues to exceed supply by four to one.15 He viewed the technology selloff as overdone and believes a more disciplined spending pace could strengthen existing data-center assets while allowing the industry to work through current financing and capacity constraints. Richard was more cautious about the capital required for the buildout, warning that tighter AI-related credit markets could force companies to issue more equity and create additional supply for public investors to absorb. Dan expects software to outperform semiconductors over the next year as attention shifts from infrastructure to practical use cases, while cybersecurity could become one of technology’s strongest areas as AI agents increase the number of systems and endpoints that must be protected. Beyond technology, the panel highlighted healthcare, defense, materials, gold, and investment-grade fixed income as attractive areas, with yields of approximately 5%–6% offering investors income and portfolio stability. Their overall message was that the AI thesis remains intact, but financing conditions, inflation, and the ability of companies to translate investment into earnings will determine which businesses emerge as the long-term winners.
So Long, New York
The message from this year’s Investment Forum was clear: the economy remains resilient, earnings are growing, productivity is improving, and market participation is beginning to broaden. Risks remain across inflation, politics, geopolitics, market concentration, and AI financing, but the speakers consistently emphasized that long-term investment themes remain intact and that periods of volatility can create attractive opportunities.
We once again thank the Hightower community, advisors, speakers, and sponsors for joining us at the Conrad in New York City, and we look forward to seeing everyone again next year!
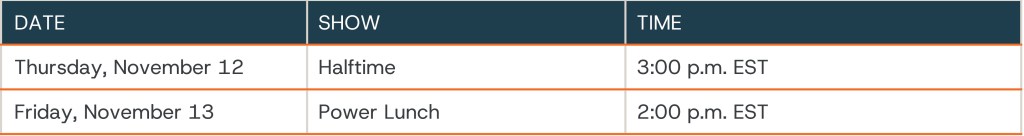
Stephanie Link’s TV Schedule
[1] Atlanta Fed GDPNow, As of November 9. 2026
[2] Bloomberg, As of November 11, 2026
[3] Bloomberg, As of November 11, 2026
[4] Deutsche Bank Analyst Note, As of August 23, 2026
[5] Bloomberg Intelligence, As of October 22, 2026
[6] Bloomberg Intelligence, As of October 22, 2026
[7] Bloomberg, As of November 11, 2026
[8] Bloomberg, As of November 11, 2025
[9] Bloomberg Intelligence, As of November 10, 2026
[10] Cognizant AI Forum, As of June 5, 2026
[11] SK Hynix 3Q26 Earnings, As of October 27, 2026
[12] Bloomberg, As of November 11, 2026
[13] Bloomberg, As of November 11, 2026
[14] Bloomberg, As of November 11, 2026
[15] Morningstar Midyear Outlook, As of September 14, 2026
This material is for general information and educational purposes only. Information is based on data gathered from what we believe are reliable sources. It is not guaranteed as to accuracy, does not purport to be complete and is not intended to be used as a primary basis for investment decisions.
Find answers to your questions about Hightower Signature Wealth
Hightower Signature Wealth is a fiduciary wealth management practice that provides investment management, financial planning, estate strategies, insurance, and banking solutions. We work with families, business owners, professionals, women, and retirees across more than 40 offices nationwide. Our advisors take the time to understand your financial priorities, develop a plan around your goals, and adjust that plan as your life and circumstances evolve.
Hightower Signature Wealth provides a broad range of wealth management services designed to address different aspects of your financial life. Our capabilities include investment management, financial planning, retirement planning, estate strategies, insurance and risk management, banking solutions, and charitable giving strategies. By considering these areas together, our advisors can develop a coordinated approach based on your goals, priorities, financial circumstances, and plans for the future.
Hightower Signature Wealth advisors work with a broad range of clients, including women, families, business owners, professionals, retirees, and high-net-worth individuals navigating major life or financial transitions. Rather than applying a generic playbook, each advisor tailors the plan to a client’s specific goals and current stage of life – from early-career decisions to multigenerational wealth transfer.
Yes. Hightower Signature Wealth advisors serve as fiduciaries, which means they are committed to acting in their clients’ interests when providing investment advice. We offer fee-based advisory services, with fees depending on the services provided and the specifics of your relationship. Your advisor will discuss the applicable fee structure with you so you can understand how you are charged and what services are included.
Hightower Signature Wealth has more than 40 offices nationwide, allowing our advisors to serve individuals, families, and organizations across the country. Depending on your location and preferences, you may be able to work with an advisor locally or connect with a team in another market. Visit our Locations page to explore our office locations, learn more about the teams in each market, and find an office near you.
Getting started with Hightower Signature Wealth is simple. Complete our online contact form with some basic information about yourself and what you are looking for, and we’ll connect you with an advisor who can discuss your needs and financial priorities. That initial conversation is an opportunity to learn more about our approach, ask questions, and determine whether working with a Hightower Signature Wealth advisor may be a good fit.
Your first conversation is an opportunity for us to learn more about you, your financial circumstances, and what you hope to accomplish. An advisor may ask about your goals, current investments, family considerations, business interests, and other priorities that could influence your financial plan. You’ll also have an opportunity to ask questions, learn about our approach, and discuss what working together could look like.