
Weekly Wisdom: Mid-Year 2026 Market Recap and Outlook
While the first half of the year presented investors with no shortage of headlines, from geopolitical tensions and evolving monetary policy to the continued acceleration of artificial intelligence, the underlying fundamentals remain encouraging. Below, we’ve summarized the key themes we believe will continue to drive investment opportunities in the months and years ahead.
Market Broadening Following Extended Tech Leadership
The largest development of the first half of the year has been the escalating conflict with Iran. The conflict resulted in the closure of the Strait of Hormuz, briefly pushing Brent oil as high as $120 per barrel and inciting increased market volatility.1 However, even despite the recent fallout between the US and Iran in ceasefire talks, tensions have overall eased allowing oil prices to retreat to ~$75 with equity markets recovering significantly.2
Even with the conflict, the first half of 2026 demonstrated a record strong market with the S&P 500 gaining approximately 9%, while the Dow Jones Industrial Average rose 10% and the Nasdaq Composite advanced 11%, outperforming historical average first-half returns.3 Early in the year, market leadership was firmly concentrated in the AI infrastructure trade. Semiconductor and memory companies experienced one of their strongest rallies in years as investors recognized the unprecedented scale of artificial intelligence capital expenditures. The VanEck Semiconductor ETF (SMH) climbed roughly 85% year-to-date at its peak, fueled by extraordinary demand across the AI supply chain. Memory manufacturers were among the biggest beneficiaries, with both Micron and SanDisk reporting that demand continues to significantly outpace available supply and that they do not expect meaningful supply-demand balance until at least 2028.4 Micron further underscored the strength of the cycle by announcing approximately $100 billion in customer commitments, including $22 billion in cash deposits, providing exceptional visibility into future demand.
Following this remarkable run, portions of the semiconductor sector began to consolidate during the latter half of the second quarter. From its June highs, the SMH declined roughly 12%, stabilizing at +64% YTD while several AI hardware leaders experienced healthy profit taking after extraordinary gains. Importantly, rather than signaling weakness, this rotation allowed capital to broaden into other areas of the market.5 During the first quarter alone, eight of the eleven S&P 500 sectors delivered double-digit earnings growth, with technology, industrials, energy, consumer staples, utilities, and financials all contributing. Healthcare, financials, cybersecurity, and other cyclical sectors have increasingly assumed leadership, reinforcing that today’s market is supported by improving corporate fundamentals rather than relying solely on a handful of mega-cap technology companies. We continue to view this rotation as constructive. While the AI investment cycle remains firmly intact, investors are increasingly recognizing that its benefits extend well beyond semiconductor manufacturers. We expect companies tied to industrial automation, electrical infrastructure, power generation, financial services, and cybersecurity to increasingly participate in the next phase of this secular expansion.
Strong Economic Fundamentals Continue to Support Growth
Despite macroeconomic uncertainty, the U.S. economy has remained remarkably resilient. GDP growth has continued at approximately 2.5% to 3.0%, supported by a healthy labor market, rising wages, and continued consumer spending. The labor market remains one of the strongest pillars of the economy.6 Job openings have averaged approximately 7.6 million, well above historical norms, while layoffs declined nearly 40% during the first half of the year. Weekly initial jobless claims have averaged approximately 220,000, remaining well below recessionary levels that historically range between 350,000 and 375,000.7 Consumer spending has remained equally impressive, growing approximately 6.3%, supported by healthy employment, wage growth between 3.5-4%, and significantly lower energy prices compared to earlier highs. Since consumer spending accounts for nearly 70% of U.S. GDP, its continued strength remains one of the most important reasons we maintain a constructive outlook.8
Inflation remains elevated but increasingly appears manageable. While AI-driven infrastructure investment continues creating supply constraints across semiconductors, memory, electrical equipment, engineering, and construction labor, lower oil prices provide an important offset. We believe inflation should continue moderating over time while remaining somewhat above the Federal Reserve’s long-term target.
Artificial Intelligence Remains a Multi-Year Investment Cycle
Artificial intelligence continues to represent one of the largest capital investment cycles in decades, and importantly, its beneficiaries extend far beyond the largest technology companies.
AI-related capital expenditures are expected to increase from approximately $800 billion this year to more than $1.1 trillion next year, benefiting semiconductor manufacturers, memory suppliers, data center builders, electrical equipment manufacturers, grid modernization companies, utilities, industrials, and power providers.9
Looking further ahead, data center investment is expected to exceed $7.1 trillion by 2030, while both electrical grid modernization and power infrastructure are projected to receive roughly $1 trillion in investment. Electricity demand is accelerating from approximately 3% annual growth today to over 11% over the coming decade as AI adoption expands globally.10 Although portions of the semiconductor industry have experienced healthy consolidations following exceptional gains, we continue viewing these periods as opportunities within what remains a long-duration investment cycle.
The Next Phase of AI: From Building to Using
For the past two quarters, markets have largely rewarded companies directly connected to supplying or building the infrastructure for artificial intelligence. Looking ahead, we believe the next major opportunity lies with businesses that successfully integrate AI throughout their operations. Previously underappreciated industries with a mixed operational history like pharmaceuticals, transportation, logistics, insurance, telecommunications, and customer service. These sectors in particular all possess significant opportunities to turnaround as they improve productivity, lower costs, and enhance customer experience through AI adoption. Rather than simply representing another technology upgrade, AI has the potential to fundamentally reshape business operations across nearly every sector of the economy. Just as smartphones evolved from communication devices into platforms that transformed daily life, artificial intelligence appears poised to become a foundational productivity tool for businesses worldwide.
Long-Term Investment Themes Continue to Strengthen
Beyond AI infrastructure itself, several long-term secular themes we laid out in our 2026 themes Outlook continue to gain momentum.
Cybersecurity remains one of our highest conviction investment themes. As AI becomes increasingly integrated into software development and enterprise operations, cybersecurity has become even more essential. Global cybercrime costs are projected to reach $10.5 trillion this year, while nearly every Fortune 500 company has experienced some form of cyberattack.11 We expect cybersecurity spending to remain a long-term structural growth opportunity.
Robotics and automation continue to benefit from advances in AI, battery technology, and machine intelligence. The installed base of humanoid and autonomous robots is expected to expand dramatically over the coming decades, creating meaningful opportunities across industrial automation, manufacturing, and semiconductor supply chains.
Quantum computing remains an earlier-stage investment theme but possesses enormous long-term potential. While commercial adoption may still be several years away, quantum computing has the potential to significantly enhance artificial intelligence, scientific research, healthcare, and financial modeling.
We also became more engaged in the theme of women’s health, wellness, and longevity. Women represent half of the global population yet continue receiving only a small fraction of healthcare investment. Areas in which women have historically been underrepresented in research, including cardiovascular disease, Alzheimer’s disease, osteoporosis, menopause, and preventative healthcare represent meaningful investment opportunities and is expected to become a nearly $400B market by 2030.12 For more information, we discussed the opportunities in women’s health in a prior weekly wisdom.
A New Era at the Federal Reserve
One of the more significant developments during the first half of the year was the appointment of Kevin Warsh as the new Federal Reserve Chair. His arrival introduced a new dynamic to monetary policy as markets balanced resilient economic growth against persistent inflation pressures.
While investors entered the year expecting several interest rate cuts, stronger-than-expected inflation data temporarily shifted expectations toward the possibility of additional tightening. Although Chair Warsh has expressed support for lower interest rates over time, policy decisions remain highly data dependent and ultimately require agreement among the full Federal Open Market Committee.
Importantly, long-term Treasury yields continue serving as a natural source of market discipline. Should inflation remain elevated, longer-term rates would likely adjust higher, limiting the Fed’s ability to ease policy too aggressively. As a result, we expect monetary policy to remain measured rather than abrupt. Within fixed income portfolios, we have modestly reduced duration while gradually upgrading overall credit quality. Credit spreads remain near historically tight levels, allowing investors to improve portfolio quality while giving up very little yield. We continue viewing fixed income as an attractive source of income, diversification, and portfolio stability.
Private Markets Continue to Expand the Opportunity Set
Private markets continue to represent an increasingly critical component of long-term portfolio construction as companies remain private for longer periods. Today, approximately 90% of companies generating more than $100 million in annual revenue remain privately held, while the number of investable private companies has expanded dramatically over the past two decades.13 Much of today’s value creation now occurs well before companies reach the public markets which was highlighted by SpaceX’s IPO value of $1.77 trillion, a record high.14 We continue to view private investments as complementary to traditional equity and fixed income allocations, offering enhanced diversification, attractive return potential, and additional sources of current income. Our focus remains on accessing opportunities across private equity, private credit, real estate, and hedge fund strategies while leveraging Hightower’s institutional relationships to provide clients with favorable structures and economics.
Expanding Our Investment Platform with Moment and PMX
Alongside favorable market developments, significant enhancements are underway across our investment platform. The rollout of Moment, Hightower’s new firm-wide order management system, represents a major advancement for both equity and fixed income portfolio management. Moment enables investment teams to implement portfolio changes more efficiently across thousands of client accounts while improving tax management, customization, compliance oversight, and execution quality. For clients, these operational improvements translate into faster implementation of investment ideas, greater portfolio consistency, and a more seamless investment experience. Together with PMX, these enhancements strengthen our ability to efficiently manage portfolios while expanding access to an increasingly diverse investment opportunity set.
The launch of PMX (Private Market Exchange) marks an important enhancement to this process. PMX streamlines the private investment experience from subscription through ongoing reporting, replacing what has traditionally been a fragmented and paperwork-intensive process with a significantly more efficient client experience. We continue to see particularly compelling opportunities across private artificial intelligence companies, cybersecurity, health and wellness, and other innovation-driven businesses that are creating substantial value before entering the public markets.
Looking Ahead
The first half of 2026 reinforced an important principle: despite periods of uncertainty, markets ultimately follow fundamentals. Today those fundamentals remain encouraging. Economic growth continues, consumers remain healthy, labor markets are resilient, corporate earnings are broadening across sectors, and one of the largest capital investment cycles in history continues to accelerate. Volatility will undoubtedly remain part of the investment landscape. However, history consistently demonstrates that waiting for complete certainty often means missing some of the most compelling long-term opportunities. We remain confident that disciplined portfolio construction, broad diversification, and continued exposure to durable secular growth themes position investors well for the second half of 2026 and beyond.
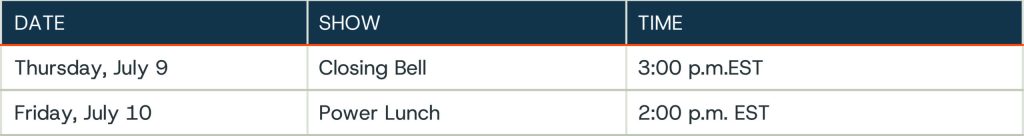
Stephanie Link’s TV Schedule:
[1] Bloomberg, as of June 22, 2026
[2] Bloomberg, as of July 8, 2026
[3] Bloomberg, as of July 8, 2026
[4] Bloomberg Intelligence, as of July 8, 2026
[5] Bloomberg, as of July 8, 2026
[6] Federal Reserve Bank of Atlanta, as of July 8, 2026
[7] UPS Analyst Note, as of July 7, 2026
[8] Deutsche Bank Analyst Note, as of July 8, 2026
[9] UPS Analyst Note, as of May 25, 2026
[10] Mizuho Analyst Note, as of April 2, 2025
[11] Wells Fargo Analyst Note, as of September 17, 2025
[12] UBS Analyst Note, as of April 19, 2026
[13] Manhattan Venture Partners, as of June 23, 2025
[14] Bloomberg, as of July 8, 2026
This material is for general information and educational purposes only. Information is based on data gathered from what we believe are reliable sources. It is not guaranteed as to accuracy, does not purport to be complete and is not intended to be used as a primary basis for investment decisions.
Find answers to your questions about Hightower Signature Wealth
Hightower Signature Wealth is a fiduciary wealth management practice that provides investment management, financial planning, estate strategies, insurance, and banking solutions. We work with families, business owners, professionals, women, and retirees across more than 40 offices nationwide. Our advisors take the time to understand your financial priorities, develop a plan around your goals, and adjust that plan as your life and circumstances evolve.
Hightower Signature Wealth provides a broad range of wealth management services designed to address different aspects of your financial life. Our capabilities include investment management, financial planning, retirement planning, estate strategies, insurance and risk management, banking solutions, and charitable giving strategies. By considering these areas together, our advisors can develop a coordinated approach based on your goals, priorities, financial circumstances, and plans for the future.
Hightower Signature Wealth advisors work with a broad range of clients, including women, families, business owners, professionals, retirees, and high-net-worth individuals navigating major life or financial transitions. Rather than applying a generic playbook, each advisor tailors the plan to a client’s specific goals and current stage of life – from early-career decisions to multigenerational wealth transfer.
Yes. Hightower Signature Wealth advisors serve as fiduciaries, which means they are committed to acting in their clients’ interests when providing investment advice. We offer fee-based advisory services, with fees depending on the services provided and the specifics of your relationship. Your advisor will discuss the applicable fee structure with you so you can understand how you are charged and what services are included.
Hightower Signature Wealth has more than 40 offices nationwide, allowing our advisors to serve individuals, families, and organizations across the country. Depending on your location and preferences, you may be able to work with an advisor locally or connect with a team in another market. Visit our Locations page to explore our office locations, learn more about the teams in each market, and find an office near you.
Getting started with Hightower Signature Wealth is simple. Complete our online contact form with some basic information about yourself and what you are looking for, and we’ll connect you with an advisor who can discuss your needs and financial priorities. That initial conversation is an opportunity to learn more about our approach, ask questions, and determine whether working with a Hightower Signature Wealth advisor may be a good fit.
Your first conversation is an opportunity for us to learn more about you, your financial circumstances, and what you hope to accomplish. An advisor may ask about your goals, current investments, family considerations, business interests, and other priorities that could influence your financial plan. You’ll also have an opportunity to ask questions, learn about our approach, and discuss what working together could look like.
