Weekly Wisdom: Banks Signal Continued Economic Strength
Banks Build on a Strong Second Quarter
This week’s bank earnings provided another encouraging read on the U.S. economy. While results naturally moderated from an exceptionally strong second quarter, particularly in trading and investment banking, the underlying trends remained healthy. Revenue continued to grow, loan and deposit balances expanded, and several banks raised their profitability or net interest income outlooks. JPMorgan’s profit increased 6% year-over-year to $15.3 billion, while revenue rose 8% to $50.2 billion. Consumer and Community Banking revenue increased 9%, and Commercial and Investment Bank revenue grew 14%, supported by a 14% increase in banking fees and 15% growth in markets revenue. Excluding $658 million of securities losses related to the bond-market selloff, earnings were $5.75 per share.1 Wells Fargo also continued to make progress, with revenue increasing 2% and net interest income growing by nearly 5% from last year. The bank maintained a stable net interest margin of 2.43%, consistent with management’s expectation that margins would stabilize or improve. Wells also continued to benefit from its efficiency initiatives, reducing headcount by 8% year-over-year and lowering non-interest expense by 1% despite continued investments in the business.2
Continued Signs of Strength Among Consumers
The clearest and most positive message from the reports was the continued strength of the U.S. consumer. Across JPMorgan, Wells Fargo, Bank of America, and Citigroup, consumers continued to spend, delinquencies remained low and credit quality held up well. JPMorgan CEO Jamie Dimon said the U.S. economy continues to be fueled by strong business investment and ongoing consumer spending. Average credit card loans increased 7% year-over-year, while card charge-offs improved to 2.91% from 3.15%.3 Wells Fargo similarly emphasized the health of its consumer and business customers. Consumers are spending more, loan delinquencies remain low, and deposit and investment balances have grown. Consumer net charge-offs totaled $983 million, below expectations, while nonperforming assets declined 6% year-over-year. Auto originations increased 15%, auto revenue grew 33%, and credit-card revenue rose 3% on higher loan balances and card fees.4
Bank of America’s spending data reinforced that message. Gas spending increased 16%, entertainment rose 13%, retail and services each grew 5%, and food spending increased 3%. Credit also remained healthy, with provisions coming in nearly 15% below expectations and management seeing no meaningful deterioration across either consumer or commercial portfolios.5 Citi also reported rising spending and improving consumer credit losses from last year. While management teams continue to acknowledge the possibility that consumer activity could eventually moderate, the banks have a direct view into spending, borrowing, and repayment behavior, and their data continue to show a consumer who is actively spending and comfortably meeting financial obligations.6 That remains an important source of support for the economy.
Loan Growth and Net Interest Income Accelerate
Loan and deposit growth were another major positive across the reports. JPMorgan’s core lending revenue and net interest income increased 13% to $27 billion. The company raised its full-year NII outlook, excluding Markets, by $1 billion to $97.5 billion and forecast $107 billion for 2027. The higher outlook reflects continued confidence in the bank’s lending operations and balance-sheet growth.7 Bank of America’s NII increased 8% year-over-year to $16.45 billion. More importantly, management raised its 2027 NII growth outlook to at least 8%, up from its previous forecast of 5%–7%. Loan growth, stronger deposits and the continued replacement of lower-yielding securities with higher-yielding loans are expected to support that improvement.8 Wells Fargo’s average loans increased by approximately $100 billion from last year, with total average loans and deposits growing 11.3% and 10.7%, respectively. Growth was led by higher balances in Corporate and Investment Banking and Commercial Banking. The company maintained its full-year NII outlook of approximately $50 billion and expects fourth-quarter NII of roughly $13 billion.9 Citigroup expects NII excluding Markets to grow in the mid-to-high 6% range in 2026, supported by client activity and deposit growth. Citi also raised its full-year return on tangible common equity outlook to above 11%, compared with its previous target of 10%–11%. Expanding loans, higher deposits, and improving NII outlooks indicate that credit demand remains healthy and provide further evidence of continued economic momentum.10
Strong Capital Markets and Wealth Management Franchises
Capital-markets activity moderated from the unusually strong second quarter, but Goldman Sachs, Morgan Stanley, and Citigroup still produced impressive results across equities, advisory, and wealth management. Goldman Sachs delivered the strongest overall report, with earnings increasing nearly 39% year-over-year to $17.01 per share. Revenue rose 23% to $18.68 billion, led by a 32% increase in Global Banking and Markets revenue. Equities revenue surged 72% to $6.44 billion, investment-banking revenue increased 21%, and advisory revenue reached a quarterly record of $1.65 billion. Goldman’s credit performance also remained strong, with net charge-offs declining 49% and provisions falling nearly 15%. The bank returned another $3 billion to shareholders through share repurchases.11 Morgan Stanley additionally reported strong figures, with revenue increasing nearly 12% and earnings rising 8%. Equities revenue jumped 41% to $5.8 billion, while Wealth Management generated record revenue of $9.07 billion. Net new assets reached $232 billion, up from $148 billion in the previous quarter, and fee-based flows totaled more than $80 billion. Across Wealth and Investment Management, total client assets reached $10.5 trillion. Management remains focused on investing in long-term growth, particularly through the scale created by E*TRADE, rather than maximizing short-term margins.12
Citigroup also reported broad-based momentum. Services revenue increased 15% to $6.6 billion, average deposits grew 16%, and the segment generated a 31.2% return on tangible common equity. Markets revenue increased 6%, including 14% growth in Equities and 4% growth in Fixed Income. Wealth revenue rose 15%, while net new investment assets reached $38 billion. Citi returned $4.1 billion to shareholders during the quarter, including approximately $3 billion through share repurchases. Citi’s investments in AI are also beginning to produce measurable benefits. AI-enabled processes have accelerated product launches by approximately 30%–40%, while 14,000 engineers now use the company’s agentic coding platform.13 Technology-vendor spending declined 30%, and management said the financial benefits from AI and automation have substantially exceeded the related investments this year. Morgan Stanley was similarly bullish on AI, describing the firm as “double overweight” on the opportunity while also beginning to invest in tokenization.14
While several headline figures initially weighed on shares, management teams across the financial sector repeatedly prepared investors for a normalization in trading, investment banking, and other market-sensitive businesses, from this we largely believe the investor reaction was largely overdone creating an attractive entry point against a positive economic backdrop. Consumers are still spending, credit quality remains healthy, loan and deposit balances continue to grow, and several banks raised their profitability or net interest income outlooks. These results should be viewed as normalization from an unusually strong quarter rather than evidence of a meaningful slowdown.
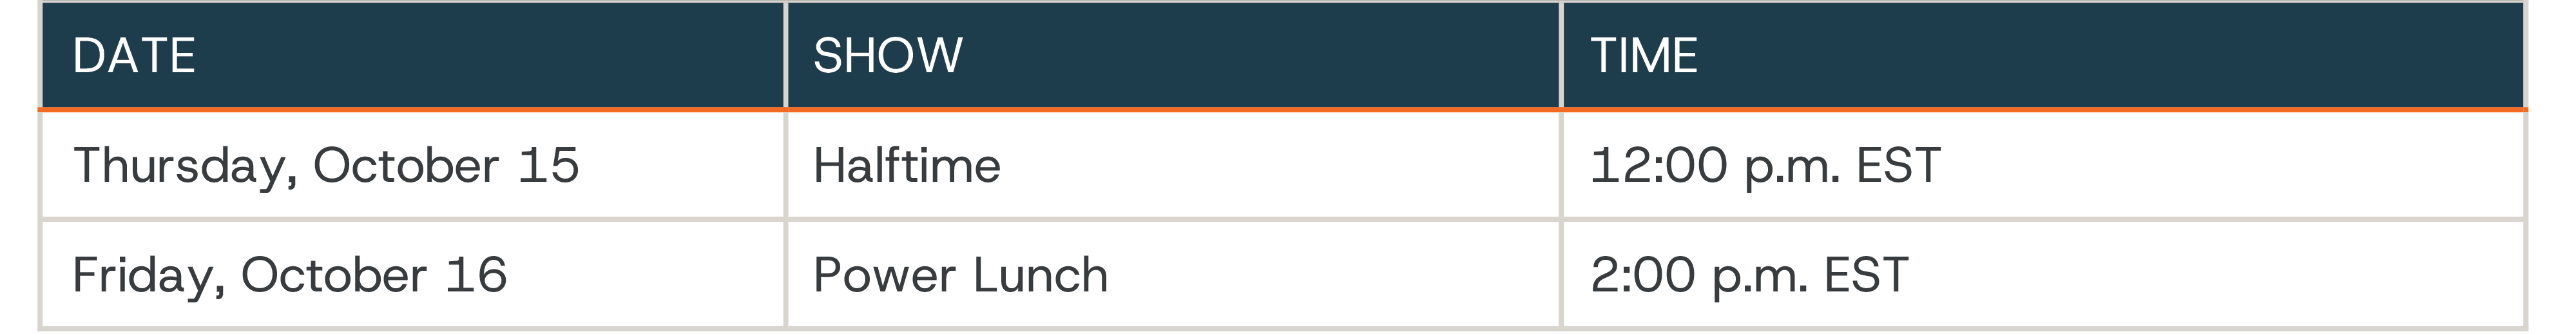
Stephanie Link’s TV Schedule
[1] JPM 3Q26 Earnings Call, as of October 13, 2026
[2] WFC 3Q26 Earnings Call, As of October 13, 2026
[3] JPM 3Q26 Earnings Call, as of October 13, 2026
[4] WFC 3Q26 Earnings Call, As of October 13, 2026
[5] BAC 3Q26 Earnings Call, As of October 14, 2026
[6] C 3Q26 Earnings Call, As of October 13, 2026
[7] JPM 3Q26 Earnings Call, as of October 13, 2026
[8] BAC 3Q26 Earnings Call, As of October 14, 2026
[9] WFC 3Q26 Earnings Call, As of October 13, 2026
[10] C 3Q26 Earnings Call, As of October 13, 2026
[11] GS 3Q26 Earnings Call, As of October 13, 2026
[12] MS 3Q26 Earnings Call, As of October 14, 2026
[13] C 3Q26 Earnings Call, As of October 13, 2026
[14] MS 3Q26 Earnings Call, As of October 14, 2026
This material is for general information and educational purposes only. Information is based on data gathered from what we believe are reliable sources. It is not guaranteed as to accuracy, does not purport to be complete and is not intended to be used as a primary basis for investment decisions.
Find answers to your questions about Hightower Signature Wealth
Hightower Signature Wealth is a fiduciary wealth management practice that provides investment management, financial planning, estate strategies, insurance, and banking solutions. We work with families, business owners, professionals, women, and retirees across more than 40 offices nationwide. Our advisors take the time to understand your financial priorities, develop a plan around your goals, and adjust that plan as your life and circumstances evolve.
Hightower Signature Wealth provides a broad range of wealth management services designed to address different aspects of your financial life. Our capabilities include investment management, financial planning, retirement planning, estate strategies, insurance and risk management, banking solutions, and charitable giving strategies. By considering these areas together, our advisors can develop a coordinated approach based on your goals, priorities, financial circumstances, and plans for the future.
Hightower Signature Wealth advisors work with a broad range of clients, including women, families, business owners, professionals, retirees, and high-net-worth individuals navigating major life or financial transitions. Rather than applying a generic playbook, each advisor tailors the plan to a client’s specific goals and current stage of life – from early-career decisions to multigenerational wealth transfer.
Yes. Hightower Signature Wealth advisors serve as fiduciaries, which means they are committed to acting in their clients’ interests when providing investment advice. We offer fee-based advisory services, with fees depending on the services provided and the specifics of your relationship. Your advisor will discuss the applicable fee structure with you so you can understand how you are charged and what services are included.
Hightower Signature Wealth has more than 40 offices nationwide, allowing our advisors to serve individuals, families, and organizations across the country. Depending on your location and preferences, you may be able to work with an advisor locally or connect with a team in another market. Visit our Locations page to explore our office locations, learn more about the teams in each market, and find an office near you.
Getting started with Hightower Signature Wealth is simple. Complete our online contact form with some basic information about yourself and what you are looking for, and we’ll connect you with an advisor who can discuss your needs and financial priorities. That initial conversation is an opportunity to learn more about our approach, ask questions, and determine whether working with a Hightower Signature Wealth advisor may be a good fit.
Your first conversation is an opportunity for us to learn more about you, your financial circumstances, and what you hope to accomplish. An advisor may ask about your goals, current investments, family considerations, business interests, and other priorities that could influence your financial plan. You’ll also have an opportunity to ask questions, learn about our approach, and discuss what working together could look like.